Antibody-Drug Conjugates (ADCs) represent an innovative and strategically engineered class of therapeutics designed to deliver potent cytotoxic agents selectively to tumor cells, thereby enhancing efficacy while minimizing systemic toxicity.
In 2025, the global ADC market experienced significant growth, with six blockbuster products with annual sales exceeding $1 billion—several of which even cleared the $2 billion mark. These milestones reflect a dual victory in clinical efficacy and commercial success, bringing new hope to cancer patients around the world.
Enhertu: Approaching $5 Billion, Leading the Industry
Companies: AstraZeneca / Daiichi Sankyo
FY2025 Global Combined Sales: $4,982 million
Combined sales of Enhertu (trastuzumab deruxtecan), recorded by Daiichi Sankyo and AstraZeneca, amounted to $4,982m in FY 2025 (FY 2024: $3,754m). US in-market sales, recorded by Daiichi Sankyo, amounted to $2,446m in FY 2025 (FY 2024: $1,864m). [1]
Enhertu's success is the result of deliberate strategy, not chance. It stems from a potent DXd payload (a topoisomerase I inhibitor) combined with a steady stream of new indications and combination therapies. Since its first approval in 2019, Enhertu has earned eight FDA approvals. Its labels now cover a massive patient population, including HER2-positive breast and gastric cancers, HER2-low and HER2-ultralow breast cancer, and HER2-mutant non-small cell lung cancer, etc.
Padcev: High-Growth Leader in Urothelial Carcinoma
Companies: Pfizer / Astellas Pharma
2025 Sales Performance:
- ● Pfizer: Reported $1,940 million in 2025 revenue, a 22% increase compared to 2024 ($1,588 million). [3]
- ● Astellas: Reported JPY 209.7 billion in total (approximately $1,400 million, comprised of JPY 162.6 billion for the first nine months of FY2025 and JPY 47.1 billion in Q4 2024). [4]
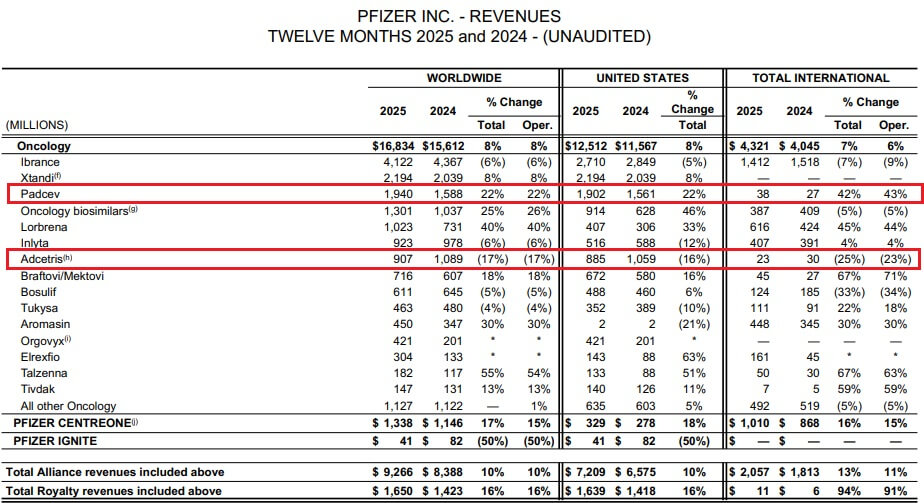
Figure 1. Pfizer revenues [3]
Padcev was one of 2025’s fastest-growing ADCs, proving that deep expertise in a specific cancer type can be a massive commercial advantage. By focusing on Nectin-4 in urothelial carcinoma and expanding into immunotherapy combinations, Padcev saw rapid adoption across the U.S. and Europe.
Since its 2019 debut in second-line advanced urothelial carcinoma, its commercial value has scaled rapidly—most notably after its 2023 approval as a first-line standard of care alongside Keytruda. By replacing traditional chemo-immunotherapy regimens, Padcev has fundamentally shifted the treatment landscape.
This momentum continues to build: on August 12, Pfizer and Astellas announced Phase 3 results showing that the Padcev-Keytruda combination significantly improves perioperative survival for patients with muscle-invasive bladder cancer (MIBC). It is set to become the foundational therapy for the entire urothelial cancer landscape.
Kadcyla: Steady Cash Flow
Company: Roche
2025 Sales: CHF 2,025 million (Approx. $2.33 billion) [5]
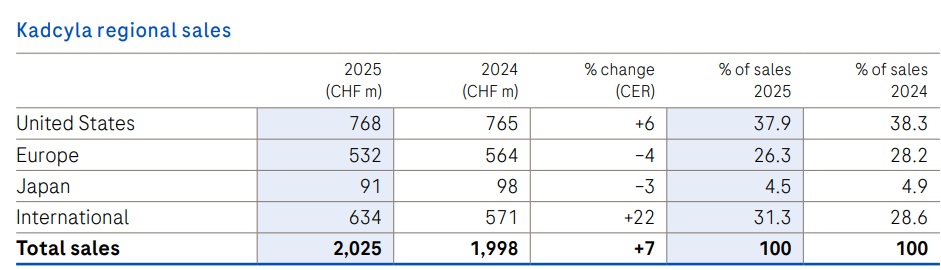
Figure 2. Kadcyla Sales 2025 [5]
Despite the aggressive market entry of Enhertu, Kadcyla remains a resilient pillar of Roche’s oncology portfolio. Its steady 7% growth is primarily driven by its established role in the adjuvant (post-surgery) breast cancer setting.
While newer competitors are increasingly dominating the metastatic market, Kadcyla’s entrenched position in early-stage therapy provides a protective moat. By maintaining its status as a standard of care in the curative setting, Kadcyla continues to serve as a reliable, long-term source of cash flow for the company.
Polivy: First-Line DLBCL Drives Sales Acceleration
Company: Roche
2025 Sales: CHF 1,470 million (Approx. $1.69 billion) [5]
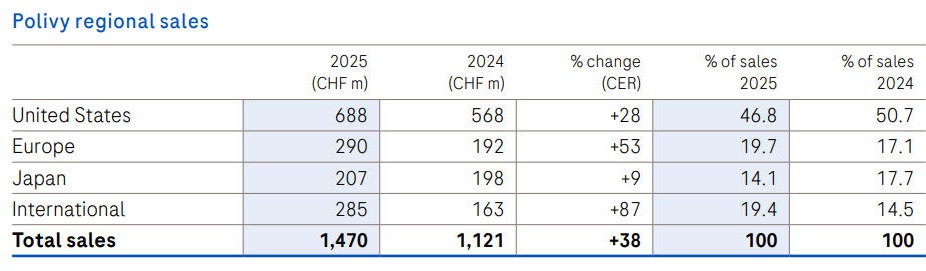
Figure 2. Polivy Sales 2025 [5]
Polivy’s impressive sales surge is primarily driven by its rapid adoption as a first-line treatment for Diffuse Large B-Cell Lymphoma (1L DLBCL). Securing a first-line position in hematological oncology is a major commercial milestone, as it offers access to a larger patient base and standardized treatment cycles, allowing the drug to scale quickly across global markets.
With more than 80,000 patients treated worldwide, the brand’s momentum is undeniable. Looking ahead, the anticipated 2026 U.S. approval of Polivy in combination with Lunsumio represents the next major catalyst, potentially opening up even more growth opportunities in the relapsed/refractory setting.
Adcetris: Entering the Mature Growth Phase
Companies: Pfizer / Takeda
2025 Sales Performance:
- ● Pfizer: Reported approximately $907 million (according to FY2025 financial disclosures). [3] Figure 1
- ● Takeda: Reported JPY 136.2 billion in total (approximately $908 million), comprised of JPY 106.8 billion for the first nine months of FY2025 and JPY 29.4 billion for the period of January to March 2025. [7]
As a mature ADC, Adcetris remains a highly valuable asset driven by a loyal prescribing base and a dominant market position. It has solidified its status as a cornerstone therapy in malignant lymphomas, particularly in the treatment of Hodgkin lymphoma.
Stability rather than rapid surges characterizes its current growth. The strategy focuses on sustainable revenue through combination regimens, incremental label expansions, and maintaining a strong presence in clinical guidelines and treatment pathways. Adcetris demonstrates that even as a product matures, it can remain indispensable by becoming deeply embedded in the standard of care.
Trodelvy: Stable Growth with Shifting Dynamics
Company: Gilead Sciences
2025 Sales: $1,397 million [6]
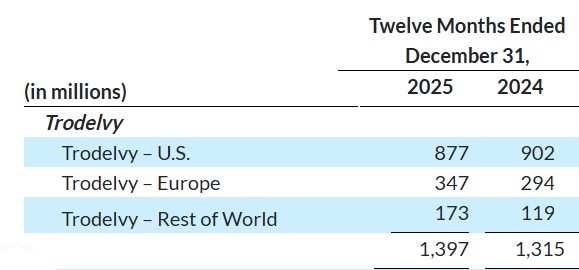
Figure 5. Trodelvy sales 2025 [6]
Trodelvy (sacituzumab govitecan) posted full-year sales of $1.397 billion, a 6% increase over the previous year. It maintains a unique competitive edge as the only ADC recommended by NCCN Guidelines for both first-line (for PD-L1+ and PD-L1- populations) and second-line treatment of metastatic triple-negative breast cancer (mTNBC).
While clinical evidence continues to solidify its role in mTNBC and HR+/HER2- breast cancer, Trodelvy’s commercial path has also been a lesson in regulatory volatility. The voluntary withdrawal of its bladder cancer indication, following confirmatory trial results, dampened overall growth. This serves as a clear strategic reminder for the industry: while aggressive label expansion is essential for scale, long-term commercial durability depends on a foundation of consistent, high-impact clinical data across every approved use.
Datroway: The Emerging Contender
Since its launch, Datroway has treated more than 3,000 patients globally, representing a 1.5x increase over the previous quarter. Sales in the U.S. and Japan have significantly outperformed initial forecasts, with U.S. growth driven primarily by the lung cancer indication.
Summary and Outlook
The 2025 data highlights three core drivers of ADC success: highly potent payloads (such as DXd), indication migration toward first-line and adjuvant settings, and pan-cancer potential.
As more combination regimens receive regulatory approval, ADCs are undergoing a fundamental shift. They are no longer just "last-resort" salvage therapies; they are rapidly becoming the cornerstones of oncology treatment. Moving forward, the industry's focus will likely remain on optimizing these "biological missiles" to reach more patients earlier in their treatment journey.
References:
[1] https://www.astrazeneca.com/content/dam/az/PDF/2025/Q4-FY/Full-year-Q4-2025-results-announcement.pdf
[2] https://www.daiichisankyo.com/files/investors/library/quarterly_result/2025/Q3/FY2025Q3_Reference_Data_E.pdf
[3] https://s206.q4cdn.com/795948973/files/doc_financials/2025/q4/Q4-2025-PFE-Earnings-Release.pdf
[4] https://www.astellas.com/content/dam/astellas-com/global/en/confidential-documents/financial-results/3q2025_en.pdf
[5] https://assets.roche.com/f/176343/x/fca190f63e/fb25e.pdf
[6] https://investors.gilead.com/news/news-details/2026/Gilead-Sciences-Announces-Fourth-Quarter-and-Full-Year-2025-Financial-Results/default.aspx
[7] https://assets-dam.takeda.com/image/upload/v1769652854/Global/Investor/Financial-Results/FY2025/Q3/qr2025_q3_qfr_en.pdf
Related Articles:
FDA Approved Antibody-Drug Conjugates (ADCs) By 2026
What Are ADC Linkers: Cleavable vs. Non-Cleavable Linkers
ADC Market 2025: Rising Sales and Growing Phase III Pipelines